ABOUT US
ABOUT US
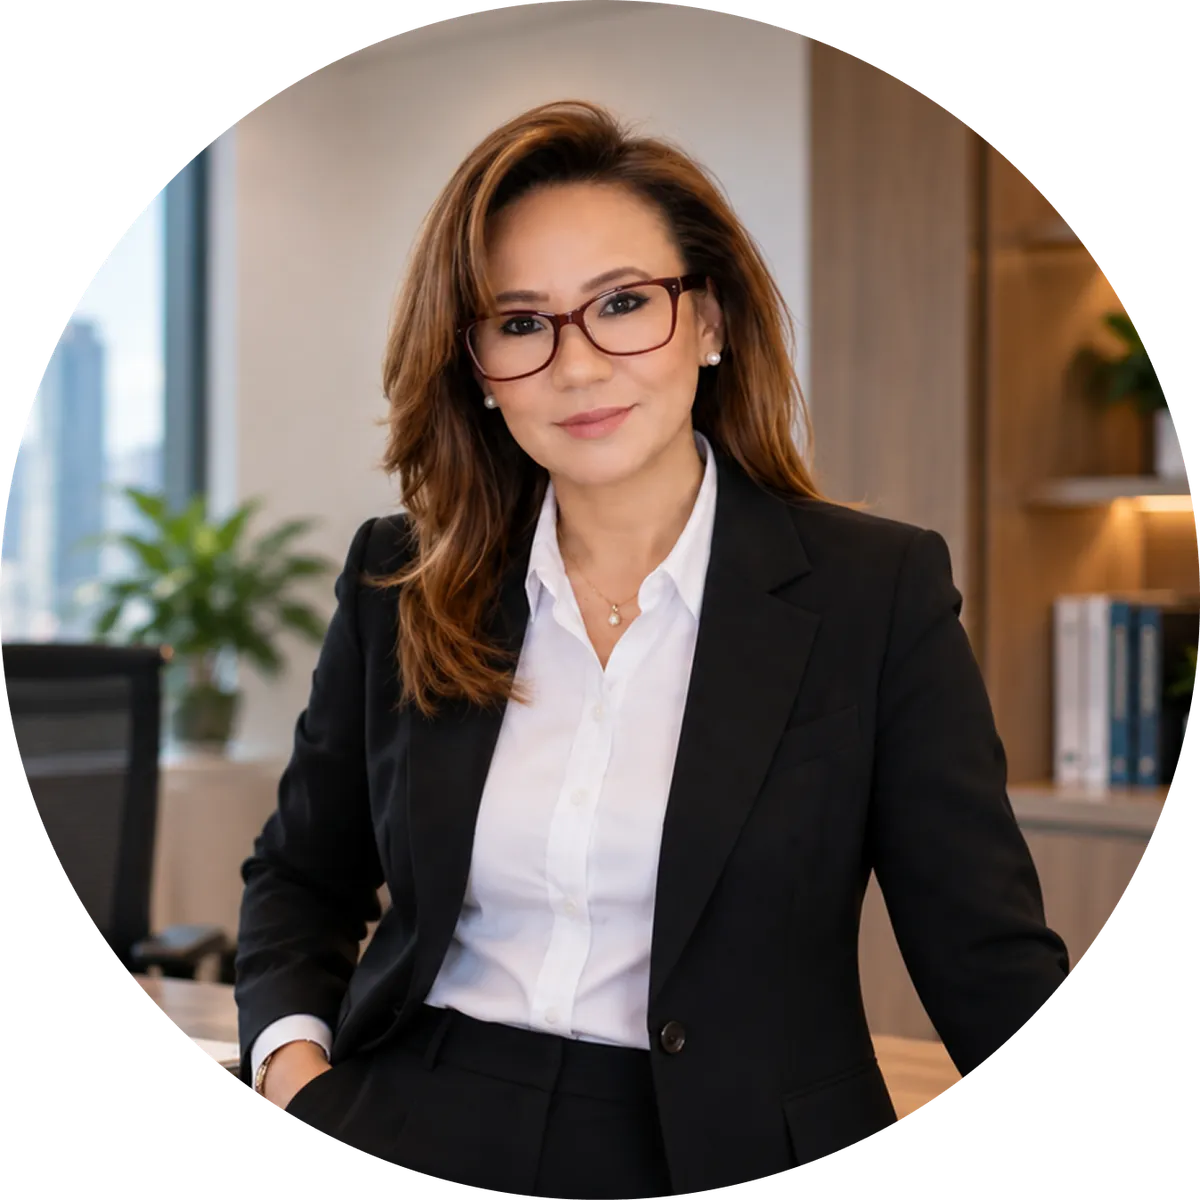
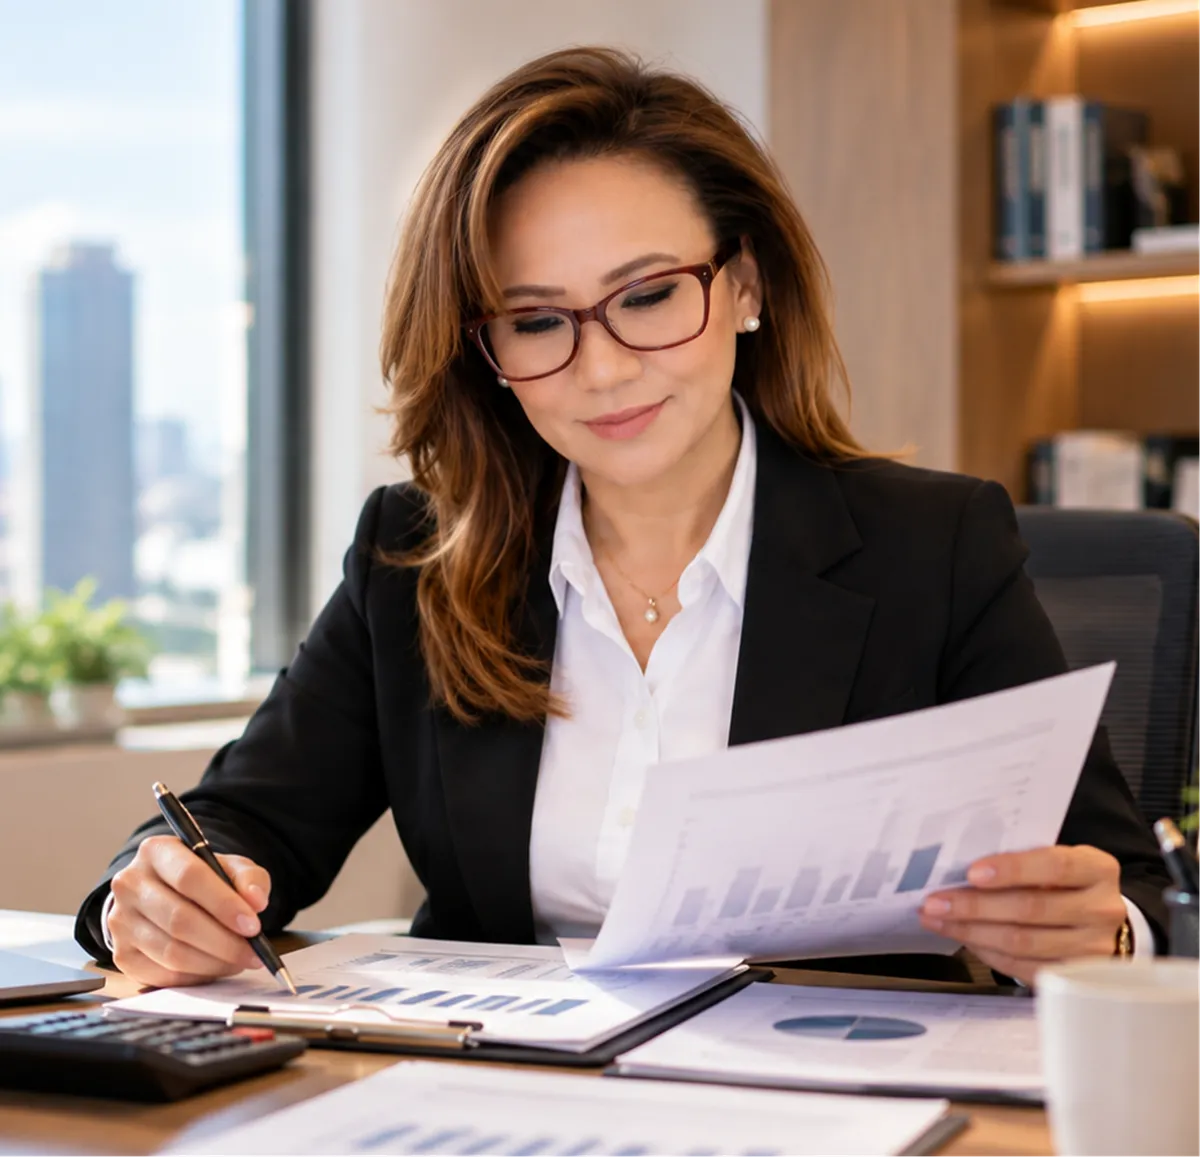
About Analiza Laguitan
Analiza built her career in education before bringing that experience into financial services, where she now helps individuals and families better understand their financial options. Before entering the industry, she spent many years working with children, families, teachers, and leaders. The experience shaped the way she communicates and explains information.
Her move into financial services started with her own retirement concerns. After years of working and saving, she began asking where her money was going, how it was working for her, and what risks, fees, and taxes could affect her future. As she learned more about retirement strategies, she realized there were financial concepts she wished she had understood earlier.
Today, Analiza works with individuals and families to make financial information easier to understand. She focuses on helping people ask better questions, understand their options, and learn how different strategies may affect their future. Her approach reflects the educator she was before entering financial services: explain the information clearly, listen to the questions, and help people understand before they make decisions.
The ERFT Philosophy
Eliminate Risk. Eliminate Fees. Eliminate Taxes.
Eliminate Risk
Strategies where the principal isn't exposed to market losses, so a downturn close to retirement doesn't reset the plan. Gains that have already been credited stay credited, which means a bad year costs you the growth you didn't get rather than the money you already had.
Eliminate Fees
Structures without the annual drag that comes out whether the account grows that year or not. A percentage taken every year is taken from a larger balance every year, which is why a number that looks small on a statement isn't small across three decades.
Eliminate Taxes
Growth and access arranged so a future tax rate doesn't decide what you keep. A tax-deferred account moves the bill rather than reducing it, and the rate that applies is the one in force when you withdraw, not the one you avoided when you contributed.
The ERFT Philosophy
Eliminate Risk. Eliminate Fees. Eliminate Taxes.
Eliminate Risk
Strategies where the principal isn’t exposed to market losses, so a downturn close to retirement doesn’t reset the plan. Gains that have already been credited stay credited, which means a bad year costs you the growth you didn’t get rather than the money you already had.
Eliminate Fees
Structures without the annual drag that comes out whether the account grows that year or not. A percentage taken every year is taken from a larger balance every year, which is why a number that looks small on a statement isn’t small across three decades.
Eliminate Taxes
Growth and access arranged so a future tax rate doesn’t decide what you keep. A tax-deferred account moves the bill rather than reducing it, and the rate that applies is the one in force when you withdraw, not the one you avoided when you contributed.
The 1% Advantage
What the wealthiest have been doing for decades
None of this is new. The structures that protect and grow wealth tax-free have been used by high-net-worth families for generations, usually through advisors most people never meet.
They aren't reserved for the wealthy and they aren't complicated. They're just not the default option inside an employer plan, so most people are never shown them.
That's the whole gap. Not access. Information.
What the wealthiest have been doing for decades
None of this is new. The structures that protect and grow wealth tax-free have been used by high-net-worth families for generations, usually through advisors most people never meet.
They aren't reserved for the wealthy and they aren't complicated. They're just not the default option inside an employer plan, so most people are never shown them.
That's the whole gap. Not access. Information.
The 1% Advantage
What the wealthiest have been doing for decades
None of this is new. The structures that protect and grow wealth tax-free have been used by high-net-worth families for generations, usually through advisors most people never meet.
They aren't reserved for the wealthy and they aren't complicated. They're just not the default option inside an employer plan, so most people are never shown them.
That's the whole gap.
Not access. Information.
What We Offer
Tax-Free Growth Strategies
Structures where the tax bill doesn't follow you into retirement.
Financial Education
So the decisions are made by you, rather than for you.
Tax-Free Growth Strategies
Structures where the tax bill doesn't follow you into retirement.
Tax-Free Growth Strategies
Structures where the tax bill doesn't follow you into retirement.
Principal Protection
Market participation without market losses.
Plans Built One at a Time
No template portfolios.
Principal Protection
Market participation without market losses.
Plans Built One at a Time
No template portfolios.
Principal Protection
Market participation without market losses.
Plans Built One at a Time
No template portfolios.
Who Analiza Works With
Individuals and families
Planning for retirement, protecting what's already been built, or setting up what passes on.
Business owners
Strategies for owners planning both their company's future and their own exit from it.
Strategic partners
Open to working with professionals whose clients face the same questions.
Let's Talk About Your Future
We invite you to reach out to us with any questions you may have about how we can help you achieve a tax-free, protected financial future. Whether you're an individual, a business owner, or interested in a strategic partnership, we're here to support you.
Let's Talk About Your Future
We invite you to reach out to us with any questions you may have about how we can help you achieve a tax-free, protected financial future. Whether you're an individual, a business owner, or interested in a strategic partnership, we're here to support you.
Let's Talk About Your Future
We invite you to reach out to us with any questions you may have about how we can help you achieve a tax-free, protected financial future. Whether you're an individual, a business owner, or interested in a strategic partnership, we're here to support you.


© 2026 Analiza Laguitan. All rights reserved.
© 2026 Analiza Laguitan.
All rights reserved.